» książki » Business & Economics - Finance - Financial Engineering


Kategoria BISAC: Business & Economics >> Finance - Financial Engineering
ilość książek w kategorii: 1232
 |
Financial Modelling with Jump Processes
ISBN: 9781584884132 / Angielski / Twarda / 552 str. Termin realizacji zamówienia: ok. 5-8 dni roboczych. WINNER of a Riskbook.com Best of 2004 Book Award
During the last decade, financial models based on jump processes have acquired increasing popularity in risk management and option pricing. Much has been published on the subject, but the technical nature of most papers makes them difficult for nonspecialists to understand, and the mathematical tools required for applications can be intimidating. Potential users often get the impression that jump and Levy processes are beyond their reach. Financial Modelling with Jump Processes shows that this is not so. It provides a self-contained... WINNER of a Riskbook.com Best of 2004 Book Award
During the last decade, financial models based on jump processes have acquired increasing popula... |
cena:
741,23 |
 |
Global Credit Review - Volume 3
ISBN: 9789814566131 / Angielski / Twarda / 176 str. Termin realizacji zamówienia: ok. 5-8 dni roboczych. Global Credit Review is an annual publication that provides an overview of the most important developments in global credit markets and the regulatory landscape. The third volume provides some critical analysis, reviews the introduction of new regulations and also offers new insights to address the challenges ahead. The carefully selected chapters touch on current topics such as: the measurement of systemic risk, reserve requirements and its role in monetary policy, the application of the Basel II default definition by credit risk assessment systems, and changes in credit portfolio...
Global Credit Review is an annual publication that provides an overview of the most important developments in global credit markets and the regulatory...
|
cena:
432,90 |
 |
Smile Pricing Explained
ISBN: 9781137335715 / Angielski / Miękka / 238 str. Termin realizacji zamówienia: ok. 5-8 dni roboczych. In modern derivatives trading, Black-Scholes theory is only a starting point. Asset volatilities are not constant, but change with market conditions. Large price moves are associated with periods of market turbulence and this leads to a smile shaped curve of the volatility implied from market prices. Smile Pricing Explained provides a clear and thorough explanation of the concepts of smile modelling that are at the forefront of modern derivatives pricing. The key models used in practice are covered, together with numerical techniques and calibration. Dr Austing guides the reader from...
In modern derivatives trading, Black-Scholes theory is only a starting point. Asset volatilities are not constant, but change with market conditions. ...
|
cena:
185,80 |
 |
The Greeks and Hedging Explained
ISBN: 9781137350732 / Angielski / Miękka / 134 str. Termin realizacji zamówienia: ok. 5-8 dni roboczych. Most books on financial derivatives focus on either the investment side of the business or on the mathematical models to price them. However, there is a gap between how quantitative researchers, analysts, structurers, risk managers and traders look and communicate on derivatives problems. In particular there often is a strong emphasis on pricing rather than hedging or risk management. This book fills a gap for a technical but not impenetrable guide to hedging options, and the 'Greek' (Theta, Vega, Rho, and Lambda) parameters that represent the sensitivity of derivatives prices. Taking the...
Most books on financial derivatives focus on either the investment side of the business or on the mathematical models to price them. However, there is...
|
cena:
156,88 |
 |
Statistics for Finance: Texts in Statistical Science
ISBN: 9781482228991 / Angielski / Twarda / 384 str. Termin realizacji zamówienia: ok. 5-8 dni roboczych. Statistics for Finance develops students professional skills in statistics with applications in finance. Developed from the authors courses at the Technical University of Denmark and Lund University, the text bridges the gap between classical, rigorous treatments of financial mathematics that rarely connect concepts to data and books on econometrics and time series analysis that do not cover specific problems related to option valuation. The book discusses applications of financial derivatives pertaining to risk assessment and elimination. The authors cover... Statistics for Finance develops students professional skills in statistics with applications in finance. Developed from the author... |
cena:
634,61 |
 |
Financial Engineering with Copulas Explained
ISBN: 9781137346308 / Angielski / Miękka / 150 str. Termin realizacji zamówienia: ok. 5-8 dni roboczych. The modeling of dependence structures (or copulas) is undoubtedly one of the key challenges for modern financial engineering. First applied to credit-risk modeling, copulas are now widely used across a range of derivatives transactions, asset pricing techniques, and risk models, and are a core part of the financial engineer's toolkit. However, by their very nature, copulas are complex and their applications are often misunderstood. Incorrectly applied, copulas can be hugely detrimental to a model or algorithm. Financial Engineering with Copulas Explained is a reader-friendly, yet rigorous...
The modeling of dependence structures (or copulas) is undoubtedly one of the key challenges for modern financial engineering. First applied to credit-...
|
cena:
144,50 |
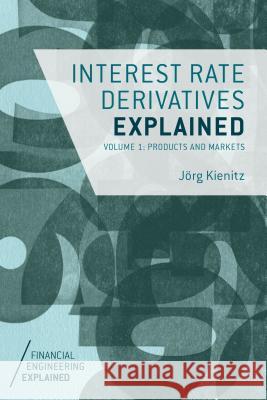 |
Interest Rate Derivatives Explained, Volume 1: Products and Markets
ISBN: 9781137360069 / Angielski / Twarda / 207 str. Termin realizacji zamówienia: ok. 5-8 dni roboczych. Aimed at practitioners who need to understand the current fixed income markets and learn the techniques necessary to master the fundamentals, this book provides a thorough but concise description of fixed income markets, looking at the business, products and structures and advanced modeling of interest rate instruments.
Aimed at practitioners who need to understand the current fixed income markets and learn the techniques necessary to master the fundamentals, this boo...
|
cena:
185,80 |
 |
Quantitative Finance: Back to Basic Principles
ISBN: 9781137414496 / Angielski / Twarda / 223 str. Termin realizacji zamówienia: ok. 5-8 dni roboczych. The series of recent financial crises have thrown open the world of quantitative finance and financial modeling. This book brings together proven and new methodologies from finance, physics and engineering, along with years of industry and academic experience to provide a cookbook of models for dealing with the challenges of today's markets.
The series of recent financial crises have thrown open the world of quantitative finance and financial modeling. This book brings together proven and ...
|
cena:
350,98 |
 |
Derivatives Analytics with Python: Data Analysis, Models, Simulation, Calibration and Hedging
ISBN: 9781119037996 / Angielski / Twarda / 384 str. Termin realizacji zamówienia: ok. 5-8 dni roboczych. Supercharge options analytics and hedging using the power of Python
Derivatives Analytics with Python shows you how to implement market-consistent valuation and hedging approaches using advanced financial models, efficient numerical techniques, and the powerful capabilities of the Python programming language. This unique guide offers detailed explanations of all theory, methods, and processes, giving you the background and tools necessary to value stock index options from a sound foundation. You'll find and use self-contained Python scripts and modules and learn how to apply... Supercharge options analytics and hedging using the power of Python
Derivatives Analytics with Python shows you how to implement mark... |
cena:
374,12 |
 |
Time-Discrete Method of Lines for Options and Bonds, The: A Pde Approach
ISBN: 9789814619677 / Angielski / Twarda / 288 str. Termin realizacji zamówienia: ok. 5-8 dni roboczych. Few financial mathematical books have discussed mathematically acceptable boundary conditions for the degenerate diffusion equations in finance. In The Time-Discrete Method of Lines for Options and Bonds, Gunter H Meyer examines PDE models for financial derivatives and shows where the Fichera theory requires the pricing equation at degenerate boundary points, and what modifications of it lead to acceptable tangential boundary conditions at non-degenerate points on computational boundaries when no financial data are available.Extensive numerical simulations are carried out with the method of...
Few financial mathematical books have discussed mathematically acceptable boundary conditions for the degenerate diffusion equations in finance. In Th...
|
cena:
481,01 |
 |
High-Frequency Trading and Probability Theory
ISBN: 9789814616508 / Angielski / Twarda / 192 str. Termin realizacji zamówienia: ok. 5-8 dni roboczych. This book is the first of its kind to treat high-frequency trading and technical analysis as accurate sciences. The authors reveal how to build trading algorithms of high-frequency trading and obtain stable statistical arbitrage from the financial market in detail. The authors' arguments are based on rigorous mathematical and statistical deductions and this will appeal to people who believe in the theoretical aspect of the topic.Investors who believe in technical analysis will find out how to verify the efficiency of their technical arguments by ergodic theory of stationary stochastic...
This book is the first of its kind to treat high-frequency trading and technical analysis as accurate sciences. The authors reveal how to build tradin...
|
cena:
379,46 |
 |
High-Frequency Trading and Probability Theory
ISBN: 9789814616515 / Angielski / Miękka / 192 str. Termin realizacji zamówienia: ok. 5-8 dni roboczych. This book is the first of its kind to treat high-frequency trading and technical analysis as accurate sciences. The authors reveal how to build trading algorithms of high-frequency trading and obtain stable statistical arbitrage from the financial market in detail. The authors' arguments are based on rigorous mathematical and statistical deductions and this will appeal to people who believe in the theoretical aspect of the topic.Investors who believe in technical analysis will find out how to verify the efficiency of their technical arguments by ergodic theory of stationary stochastic...
This book is the first of its kind to treat high-frequency trading and technical analysis as accurate sciences. The authors reveal how to build tradin...
|
cena:
203,09 |
 |
Zero Lower Bound Term Structure Modeling: A Practitioner's Guide
ISBN: 9781137408327 / Angielski / Twarda / 409 str. Termin realizacji zamówienia: ok. 5-8 dni roboczych. Nominal yields on government debt in several countries have fallen very near their zero lower bound (ZLB), causing a liquidity trap and limiting the capacity to stimulate economic growth. This book provides a comprehensive reference to ZLB structure modeling in an applied setting.
Nominal yields on government debt in several countries have fallen very near their zero lower bound (ZLB), causing a liquidity trap and limiting the c...
|
cena:
454,22 |
 |
Finance Monsters: How Massive Unregulated Betting by a Small Group of Financiers Propelled the Mortgage Market Collapse Into a Global Fi
ISBN: 9781503012400 / Angielski / Miękka / 250 str. Termin realizacji zamówienia: ok. 5-8 dni roboczych. What was the real reason for the worst financial crisis the world has seen since the Great Depression of the 1930s? Was the problem really subprime mortgages? Predatory lending? Fannie Mae, Freddie Mac and government policy? Rating Agencies failing to do their job? Banks too big to fail? Or was it something else? Inside these pages, Howard B. Hill points to another reason why the financial gears of our global economy froze in 2008. As a Wall Street professional for over 25 years, Hill was one of the key individuals responsible for building the mortgage securitization market, and he...
What was the real reason for the worst financial crisis the world has seen since the Great Depression of the 1930s? Was the problem really subprime mo...
|
cena:
70,27 |
 |
Financial Reporting: Reporting
ISBN: 9781505301854 / Angielski / Miękka / 84 str. Termin realizacji zamówienia: ok. 5-8 dni roboczych. This book is for all the business men and woman as well as degree student, it specialize explain the financial reporting and all the accounting standards in used when preparing financial statement.
This book is for all the business men and woman as well as degree student, it specialize explain the financial reporting and all the accounting standa...
|
cena:
70,48 |
 |
Probability and Finance Theory (Second Edition)
ISBN: 9789814641920 / Angielski / Twarda / 536 str. Termin realizacji zamówienia: ok. 5-8 dni roboczych. This book is an introduction to the mathematical analysis of probability theory and provides some understanding of how probability is used to model random phenomena of uncertainty, specifically in the context of finance theory and applications. The integrated coverage of both basic probability theory and finance theory makes this book useful reading for advanced undergraduate students or for first-year postgraduate students in a quantitative finance course. The book provides easy and quick access to the field of theoretical finance by linking the study of applied probability and its...
This book is an introduction to the mathematical analysis of probability theory and provides some understanding of how probability is used to model ra...
|
cena:
432,90 |
 |
Je valorise ma start-up: Comment et pourquoi déterminer une valeur transactionnelle avant de solliciter des investisseurs ?
ISBN: 9781507660447 / Francuski / Miękka / 250 str. Termin realizacji zamówienia: ok. 5-8 dni roboczych. Start-uppers soyez vigilants: les capitaux-risqueurs ont l'art de vous faire les poches avec le sourire. Et pour survivre au marathon d'une levee de fonds, il est souvent crucial de suivre des regles tacites et de decrypter certains codes secrets. Certains investisseurs, sympathiques et machiaveliques a la fois, profitent de l'innocence des entrepreneurs, peu surs d'eux au moment de negocier la valeur et le partage de la start-up. Les enfants terribles du capital-risque ont un cote obscur, des lors ne vous fiez pas, aveuglement, a leur air enjoleur. Ne devenez pas le jouet de ces "fauves...
Start-uppers soyez vigilants: les capitaux-risqueurs ont l'art de vous faire les poches avec le sourire. Et pour survivre au marathon d'une levee de f...
|
cena:
165,82 |
 |
The XVA of Financial Derivatives: CVA, DVA and FVA Explained
ISBN: 9781137435835 / Angielski / Twarda / 218 str. Termin realizacji zamówienia: ok. 5-8 dni roboczych. This latest addition to the Financial Engineering Explained series focuses on the new standards for derivatives valuation, namely, pricing and risk management taking into account counterparty risk, and the XVA's Credit, Funding and Debt value adjustments.
This latest addition to the Financial Engineering Explained series focuses on the new standards for derivatives valuation, namely, pricing and risk ma...
|
cena:
289,03 |
 |
Model Risk in Financial Markets: From Financial Engineering to Risk Management
ISBN: 9789814663403 / Angielski / Twarda / 384 str. Termin realizacji zamówienia: ok. 5-8 dni roboczych. The financial systems in most developed countries today build up a large amount of model risk on a daily basis.
The financial systems in most developed countries today build up a large amount of model risk on a daily basis.
|
cena:
630,65 |
 |
The Complete Guide to CONSULTING ENGINEERING: How to Start & Manage an Outstanding CONSULTING ENGINEERING PRACTICE
ISBN: 9780990512004 / Angielski / Miękka / 316 str. Termin realizacji zamówienia: ok. 5-8 dni roboczych. In essence, readers discover "step-by-step" how to start & manage an "outstanding" Engineering Practice and exactly how to gain a reputation as an expert in their specialty. This is both a handbook for new engineers and a constant reference manual for seasoned professionals. The book is divided into "five parts" Preparation; Planning; Implementation; Managing; and Cashing Out. PREPERATION includes: - Selecting a collage. Make sure that it has the right accreditation to allow you take the Professional Engineering license exam. (ABET-EAC accredited) - Take the EIT exam. In your senior year... In essence, readers discover "step-by-step" how to start & manage an "outstanding" Engineering Practice and exactly how to gain a reputation as an ... |
cena:
172,45 |


Czytaj nas na:
KrainaKsiazek.PL - Księgarnia Internetowa